Market overview and structural scope of the Category Management Software Market
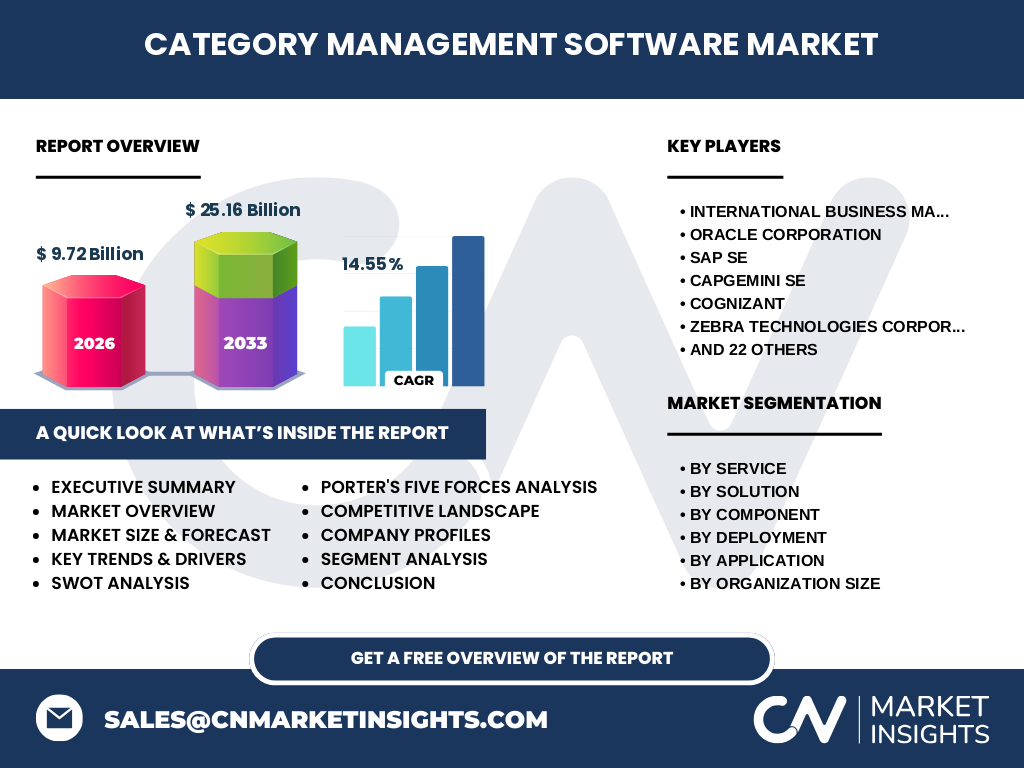
Our analysis indicates that the Category Management Software Market commands a baseline valuation of 9.72 Billion in 2026. This ecosystem governs merchandising, assortment planning, and supply chain alignment for retail and consumer packaged goods giants navigating complex global trade regulations.
What are the primary market drivers and restraints shaping the Category Management Software Market?
Growth is accelerated by omnichannel retail demands, while data privacy mandates like GDPR act as friction points. Enterprises increasingly rely on Cloud-Based Solutions to bypass legacy infrastructural bottlenecks and comply with localized consumer protection laws.
Emerging tech trends and growth patterns in the Category Management Software Market
The market is witnessing a profound shift toward predictive analytics and automated shelf-space optimization. Industry leaders leverage platforms from Snowflake Inc and Salesforce Inc to synthesize disparate point-of-sale data streams into actionable merchandising strategies.
How did COVID-19 impact the Category Management Software Market and steer recovery?
Pandemic-induced supply chain disruptions forced retailers to rapidly adopt agile inventory frameworks. The subsequent recovery trajectory vaulted software adoption, prioritizing real-time visibility tools provided by innovators like RELEX Solutions and Manhattan Associates Inc.
Competitive Benchmarking within the Category Management Software Market
The competitive landscape features high market consolidation among enterprise giants. Corporations like Oracle Corporation, SAP SE, and International Business Machines Corporation dominate through comprehensive suite integration, contrasting with agile specialists focusing on niche retail analytics.
Executive Summary of Category Management Software Market industry trends
Driven by a robust 14.55% CAGR, the sector is projected to surge toward 25.16 Billion by 2033. This expansion reflects an imperative for digital transformation across retail and distribution networks striving to optimize working capital.
Market forecast trajectory from 2027 to 2033
Based on our research, accelerated enterprise cloud migration will propel market valuation from 2027 through 2033 to reach 25.16 Billion. Investment priorities will heavily favor scalable SaaS architectures over rigid, on-premise deployments.
Segmentation analysis across solutions, services, and deployments
The market bifurcates into solutions and services, with Cloud-Based Solutions leading deployment preferences. By application, Retail and Consumer Packaged Goods capture primary spend, while SMEs increasingly adopt modular tools tailored for lean operations.
Geographic distribution and regional market performance
North America retains dominant market share, bolstered by advanced retail infrastructures and high enterprise IT spending. Meanwhile, Asia-Pacific emerges as a high-velocity growth frontier due to rapid e-commerce proliferation and modernizing distribution networks.
In-depth regional review of compliance and logistical hurdles
European markets prioritize strict data sovereignty regulations, favoring vendors offering localized data residency. Conversely, North American deployments focus on high-throughput supply chain integrations interfacing with major freight hubs and logistics networks.
Strategic positioning of leading company profiles
Industry heavyweights like TCS Tata Consultancy Services, Wipro Limited, and Capgemini SE provide vital systems integration. Concurrently, product pioneers such as Anaplan Inc and SAS Institute Inc deliver advanced predictive modeling capabilities.
Porter's Five Forces assessment of the Category Management Software Market
Competitive rivalry is intense among established enterprise vendors, while buyer power remains moderate due to high switching costs. Supplier power is tempered by open-source data standards, though proprietary AI algorithms maintain defensive moats for top-tier software providers.
SWOT analysis of sector dynamics
Key strengths lie in advanced predictive merchandising algorithms, whereas high implementation costs represent a notable weakness. Opportunities abound in emerging retail markets, though data security vulnerabilities and tightening compliance mandates pose ongoing threats.
Value chain analysis from raw data inputs to end-user retail execution
The value chain originates with raw point-of-sale data collection, flows through cloud computing infrastructure providers like Snowflake Inc, and culminates in actionable merchandising insights deployed by enterprise category managers across global retail chains.
Investment insights and high-potential areas
High-potential capital allocation targets AI-driven assortment optimization and automated supply chain replenishment tools. Investors should monitor specialized vendors like RELEX Solutions and Jaggaer LLC for above-market growth capture.
Conclusion and key strategic takeaways for industry stakeholders
Reaching 25.16 Billion by 2033 underscores a permanent digital pivot in retail merchandising. Organizations failing to adopt advanced cloud-based category management tools risk margin erosion in an increasingly automated, data-driven commercial landscape.
Research methodology for baseline estimates and validation
Our baseline estimates are rigorously triangulated by cross-referencing corporate trade registries, primary stakeholder interviews with C-level retail executives, and secondary macroeconomic indicators governing global software expenditure patterns.
Scope of the report and analytical limitations
This report covers global enterprise software deployments across retail, distribution, and CPG sectors through 2033. Excluded from this scope are localized, custom-built proprietary internal tools developed exclusively for single-enterprise use without commercial licensing.
Recent developments in partnerships, product launches, and strategic moves
Recent market momentum features strategic cloud partnerships and AI module integrations by firms like SymphonyAI Retail CPG and Board International. These moves aim to accelerate real-time decision-making capabilities for time-sensitive retail category managers.